
WEEKLY MARKET REPORT · WEEK OF NOV 16–20, 2026
AI rout drives the S&P 500 down 8.6% into a correction and the Nasdaq down 10%; the VIX closes at 35.89
The week in brief
The S&P 500 fell 8.61% for the week to 6,910.39, its worst weekly loss in more than 18 months, and closed Friday more than 10% below its Oct. 6 record high, a correction. The Nasdaq Composite lost 10.02% to 22,617.73 and is now down 2.7% for the year, the Dow fell 8.02% (4,200.22 points) to 48,147.33, and the Russell 2000 fell 7.48%. The S&P 500 closed lower every day and has now lost seven sessions in a row.
Friday was the sharpest leg: the S&P 500 fell 3.70%, the Nasdaq 5.28%, the Dow 1.93% and the Russell 2000 2.76%. Technology fell 7.27% and Consumer Staples (+0.67%) was the only S&P 500 sector to rise. Nvidia fell 14.01% to $125.53 and was down about 22.9% on the week; press reports said SEC enforcement staff are examining potential accounting issues at the company. Anthropic (ANT), which priced at $83 and began trading Thursday, closed that day up 17% and fell 8.5% on Friday.
The VIX closed at 35.89 on Friday, up 26.20% on the day and from 19.30 a week earlier, its highest close since late March. Treasury yields fell across the curve: the 2-year lost 25 basis points on the week to 4.63%, the 5-year 27 bp to 4.71%, the 10-year 23 bp to 4.92% and the 30-year 16 bp to 5.31%. The October FOMC minutes showed nearly all policymakers expecting to raise rates, and Kalshi priced a 90% chance of a 25 bp hike on Dec. 9.
Gold futures fell about 8.9% on the week to roughly $3,539, silver and copper also fell sharply, WTI fell for a third straight week to $83.98, the dollar index rose 0.42% to 103.84, and Bitcoin fell below $60,000 for the first time since July (about $58,900). Next week is shortened for Thanksgiving: October PCE and the second estimate of Q3 GDP are due Wednesday, Dell and Workday report Tuesday after the close, U.S. markets are closed Thursday and stocks close at 1:00 PM ET on Friday.
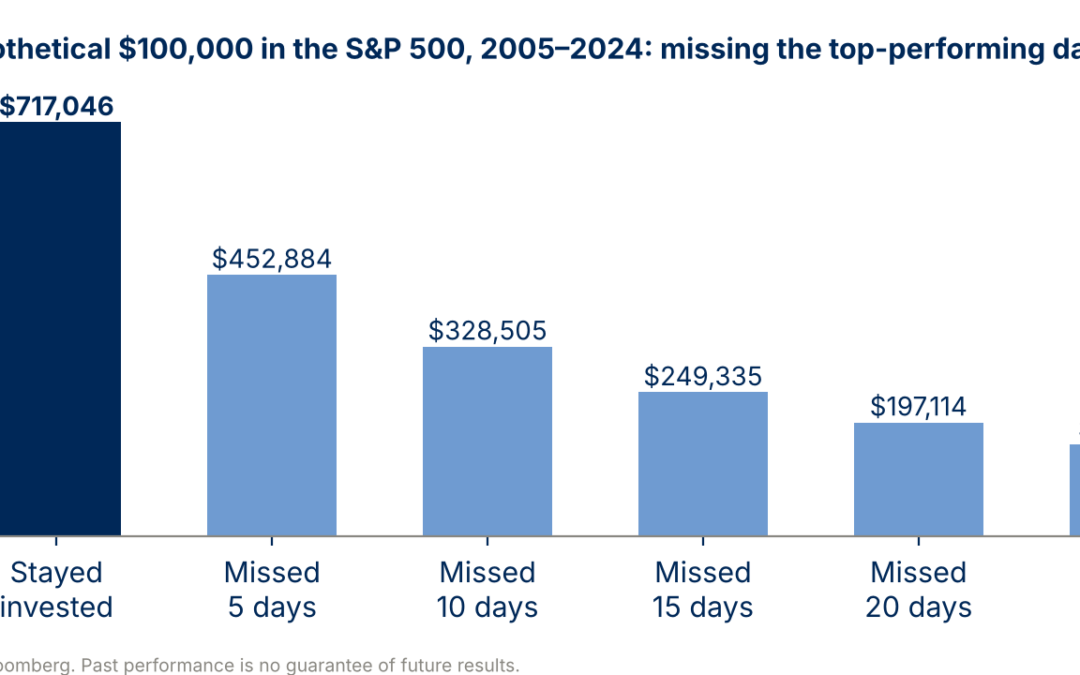
A longer view: sharp sell-offs are uncomfortable, but BlackRock’s “Strategies for Volatile Markets” analysis illustrates what stepping aside can cost. A hypothetical $100,000 invested in the S&P 500 from Jan. 1, 2005 to Dec. 31, 2024 would have grown to $717,046 if it stayed invested for the entire period, but to only $452,884 if the investor missed just the five top-performing days, $328,505 if they missed 10, and $158,792 if they missed 25. Source: BlackRock; Bloomberg. Past performance is no guarantee of future results. Clients with questions about their own portfolios are welcome to join Monday’s call.

What is capitulation? Market capitulation is the point at which investors who have held on through a decline finally sell in large numbers; it is often associated with heavy trading volume, spiking volatility and large outflows from stock funds. Friday’s sell-off left little place to hide: all four major U.S. indexes, ten of the eleven S&P 500 sectors, gold, silver, copper, Bitcoin and equity markets across Europe and Asia fell, with only Consumer Staples, Treasuries and a few commodities (crude oil and natural gas) higher. It also showed some of the features of capitulation: the VIX closed Friday at 35.89, its highest close since late March, and 376 S&P 500 stocks declined against 123 advancers. But capitulation is hard to identify in the moment and is generally recognized only in hindsight, a decline can deepen before it ends, and many dips are followed by rebounds. In our view, while there may be more room to the downside, the market looks technically oversold after an 8.6% weekly decline and seven straight losing sessions in the S&P 500. There also appeared to be forced selling, with press reports of leveraged positions being cut as gold and Bitcoin fell alongside stocks, and in our view that reduction in leverage should help. Valuations also look quite compelling to us with the earnings outlook still strong. We are not calling a bottom; the point is that decisions made at moments of peak fear are difficult to get right, which is why long-term investors with a plan often look past them.
Index scorecard
| Index | Close | Week | YTD |
| S&P 500 | 6,910.39 | -8.61% | +0.9% |
| Dow | 48,147.33 | -8.02% | +0.2% |
| Nasdaq | 22,617.73 | -10.02% | -2.7% |
| Russell 2000 | 2,581.79 | -7.48% | +4.0%
|


Treasury yields on the week: 2-yr 4.63% (-25 bp), 5-yr 4.71% (-27), 10-yr 4.92% (-23), 30-yr 5.31% (-16). WTI $83.98, Brent $92.57, gold ≈$3,539, Bitcoin ≈$58,900. Weekly: gold -8.94%, dollar index +0.42%, Bitcoin -7.85%; WTI ≈ -5.2%, Brent ≈ -3.4%, silver ≈ -16.5%, copper ≈ -10.2% are derived and approximate
Key events
- October retail sales (Nov. 17): +0.2% m/m, in line with forecasts and slowing from +0.8% in September; ex-autos +0.6%. Total sales were $748.2B, +6.8% y/y, and regular gasoline averaged a record $4.31 a gallon in October.
- Housing (Nov. 18): October housing starts 1.309M vs. 1.250M expected; building permits 1.295M vs. 1.375M expected, a 6.5-year low; pending home sales -4.7% m/m vs. -2.0% expected. MBA 30-year mortgage rate 7.35% (from 7.21%).
- Initial jobless claims (week ended Nov. 14): 203,000 vs. 197,000 expected; prior week 202,000. The October jobs report (+165,000 payrolls, 4.1% unemployment) was released Nov. 6.
- Nvidia (NVDA): reported fiscal third-quarter results after the close on Tuesday, Nov. 17; profit and revenue beat expectations and the current-quarter forecast was better than expected. CFO and interim CEO Colette Kress said: “Our momentum is real.” Shares fell 14.01% Friday to $125.53 and about 22.9% on the week Press reports said SEC enforcement staff are examining potential accounting issues; an inquiry does not establish wrongdoing. California Attorney General Rob Bonta sent an investigative subpoena late Thursday over whether its chips reached China.
- Anthropic (ANT): priced its IPO at $83; the debut closed up 17% on Thursday. Shares fell 8.50% Friday to $88.91, 7.1% above the IPO price. Seaport Research initiated at Neutral.
- Retail: TJX rose 9.9% Wednesday after CEO Ernie Herrman said he expects momentum to accelerate through the holiday season, and Target rose 5.8% on its strongest quarterly sales gain in about five years. Gap rose 11.44% Friday on adjusted EPS of $0.82 vs. $0.78 expected, though it lowered its full-year outlook; Ross Stores fell 2.92% on fourth-quarter EPS guidance of $2.16–$2.25 vs. $2.28 expected.
- FOMC minutes (Oct. 27–28 meeting), released Wednesday: nearly all policymakers said they would likely have to raise rates “in the months ahead,” and two said a hike of more than 25 bp could be warranted in December if inflation data disappoint.
- Trump in Asia: President Trump traveled to the APEC summit in Shenzhen, China, where press reports said he, President Xi Jinping and President Vladimir Putin shook hands at Wednesday’s (Nov. 18) welcome banquet. On Thursday (Nov. 19) Trump held separate talks with Xi and with Putin, followed by the first trilateral meeting of the three leaders, which lasted roughly an hour to 80 minutes, depending on the report.
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third-party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.